Please note that since publication of this article, HM Treasury has announced a new statutory framework that will be developed alongside the FCA, introducing protections for face-to-face banking. This piece presents a clear use case for protecting access to essential banking services for people, communities and small businesses.
Digital banking has a blind spot. The Post Office might have the answer.
Neobanks have spent the past decade proving you don’t need branches to build a bank. But could the next breakthrough in digital onboarding come from using someone else’s?
The industry has become remarkably good at opening accounts in minutes. Until the selfie fails, the passport won’t scan, or a legitimate customer simply can’t get through identity verification.
And the problem isn’t insignificant. Signicat’s 2026 research found that 60% of European consumers surveyed had abandoned an online financial application in the past year. Not all of those abandonments were caused by identity checks, but it’s a striking reminder that optimising the fastest route through onboarding doesn’t necessarily help everyone complete it.
GOV.UK One Login offers an interesting example.
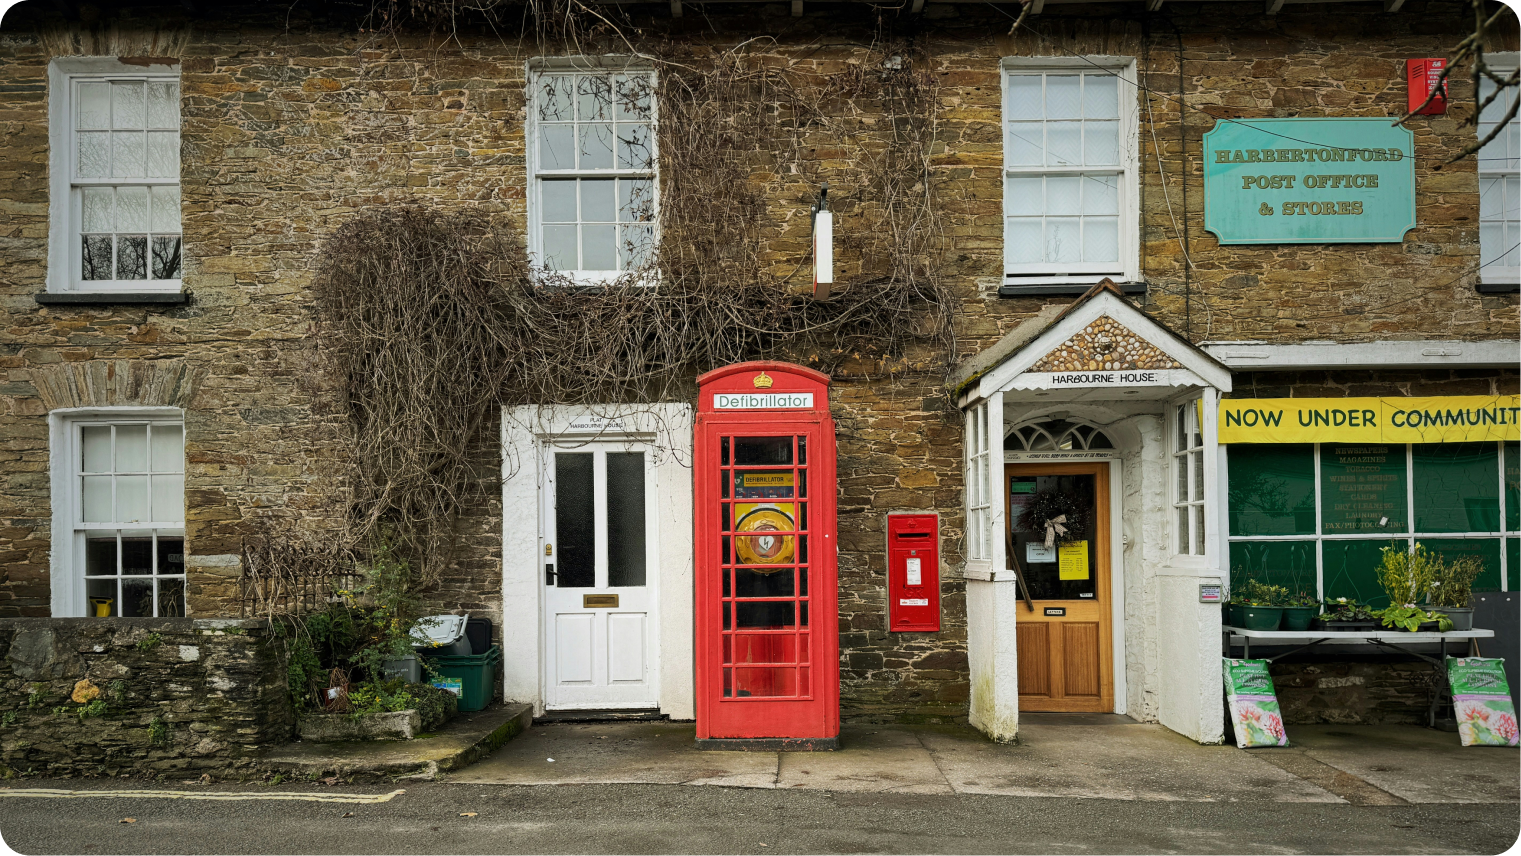
By connecting digital identity verification to participating Post Office branches, it’s found a way to bring physical infrastructure into the customer journey without having to own it.
For digital-first banks, this presents an interesting possibility. Rather than investing in their own physical networks, why not partner with organisations that already have them? Existing infrastructure could become an extension of digital onboarding, giving customers an alternative when automated verification fails, without compromising the digital-first business model.
It raises an interesting question:
Have fintechs become so focused on removing physical touchpoints that they’ve overlooked the value of bringing them back, without owning the infrastructure?
Accessibility isn’t an edge case. It’s good service design.
In Good Services, Lou Downe makes the case for designing services that work for everyone, recognising that people have different needs and circumstances.
It’s a principle that feels particularly relevant to digital banking. Whether it’s an inaccessible verification process, an unsupported device or a document that won’t scan, the issue isn’t necessarily with the customer. It’s that the service hasn’t provided a suitable way forward.
Designing with accessibility in mind often improves the experience for everyone. Clearer instructions, better recovery journeys, human assistance and alternative verification methods make onboarding more resilient, inclusive and potentially more commercially effective.
For fintechs, this creates an interesting opportunity to rethink how digital and physical services work together. Innovation doesn’t always mean replacing what’s come before. Sometimes it means finding smarter ways to connect what already exists.